Prevailing Wage and Fringe Benefits on Certified Payroll
A Davis-Bacon prevailing wage has two parts: a basic hourly rate and an hourly fringe benefit amount, listed side by side in the wage determination for each classification. The contractor must pay at least the sum of the two. The basic rate must be paid in cash. The fringe part can be met by contributions to bona fide benefit plans, by paying the equivalent in cash on top of the basic rate, or by a combination, and the certified payroll shows which. A rate that looks generous but leaves the fringe unmet is the most common finding on a reviewed payroll.
Watch it done, 2:34. A rate change on the sample project in EG Certified Payroll: the new basic rate and fringe entered from a date, the earlier rate kept in the history, the approved week still at the old rate, and the next week checked against the new sum and fixed before Approve.
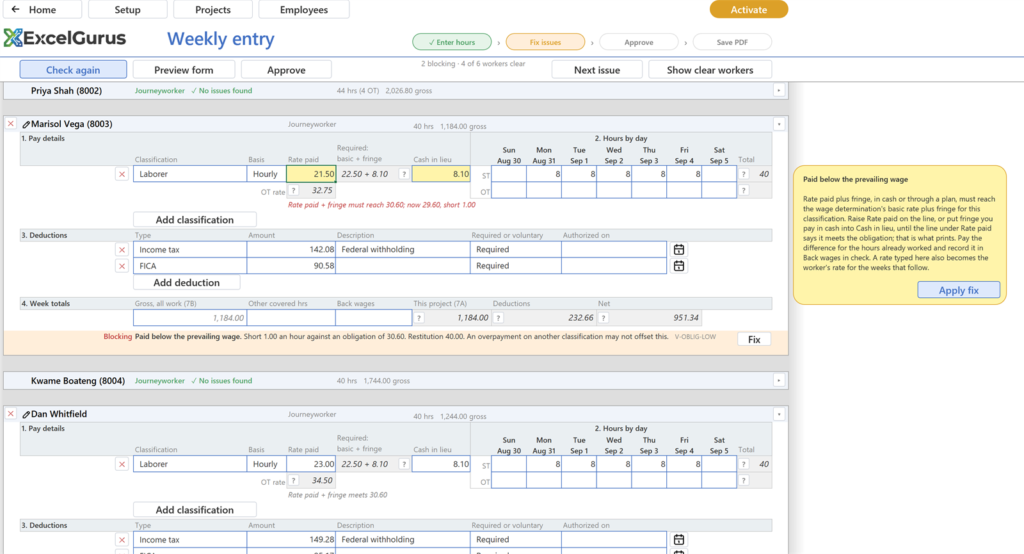
The dollar-short row from the table above, as a check finds it: 21.50 plus 8.10 against an obligation of 30.60. Screen from EG Certified Payroll (WH-347), the Excel workbook that does this.
Reading the determination
A line in a wage determination reads something like: Laborer, rate 22.50, fringes 8.10. The obligation for an hour of laborer work is 30.60. The contract clause, 29 CFR 5.5(a)(1), says the contractor may discharge the fringe part by paying the benefits as stated, by paying another bona fide fringe benefit, or by paying an hourly cash equivalent. Any mix that reaches 30.60 in total, with at least 22.50 of it in cash, complies.
| How it is paid | Cash rate | Plan contributions per hour | Cash in lieu per hour | Meets 30.60? |
|---|---|---|---|---|
| All in cash | 22.50 | 0.00 | 8.10 | Yes |
| Health plan covers part | 22.50 | 5.00 | 3.10 | Yes |
| Higher cash rate, no plan | 30.60 | 0.00 | 0.00 | Yes |
| Cash rate a dollar short | 21.50 | 0.00 | 8.10 | No, short 1.00 an hour |
The last row is the classic error. The cash rate is close, the fringe is being paid, and the payroll is still a dollar an hour short for every hour worked, which becomes restitution owed with interest.
What counts as a fringe benefit
The Act lists the kinds of benefits that count: medical or hospital care, pensions on retirement or death, compensation for injuries or illness from occupational activity, insurance to provide any of those, unemployment benefits, life insurance, disability and sickness insurance, accident insurance, vacation and holiday pay, defraying the costs of apprenticeship or similar programs, and other bona fide fringe benefits. Contributions must be made irrevocably to a trustee or third party under a bona fide plan, or be paid in cash.
What never counts: anything the law already requires the employer to pay. FICA, workers’ compensation premiums and unemployment insurance are legal obligations, not fringe benefits, and cannot be credited against the determination. Neither can the contractor’s own administrative costs, travel and lodging for workers sent away from home, the use of a company truck, or a holiday bonus.
Unfunded plans
A plan where the contractor sets money aside on its own books rather than paying a third party is an unfunded plan. Credit for an unfunded plan needs the Department of Labor’s prior approval under 29 CFR 5.28; without it, the contribution does not count and the fringe must be paid another way.
A plan’s yearly cost as an hourly credit
A plan is usually paid by the month or by the year, but the fringe in a wage determination is an hourly amount. To get from one to the other, the contractor annualizes: divide what the plan cost for the period by every hour the worker worked in that period, private work and covered work together. The result is the hourly credit that counts against the fringe. A health plan that costs 4,160 a year for a worker who works 2,080 hours that year is a credit of 2.00 an hour. If the same worker works 2,600 hours, the credit is 1.60 an hour.
Two things follow. Dividing by the covered hours alone overstates the credit, and the shortfall shows up as unpaid fringe. And where the plan costs a different amount for different workers, each worker’s credit is worked out on its own. The rule is 29 CFR 5.25(c), added in 2023. It has narrow exceptions, for example some defined contribution pension plans with immediate vesting; without one, annualize.
Watch it done, 2:31. This section’s rule on the sample project in EG Certified Payroll: a health plan set up once, a worker enrolled at 4,160 a year over 2,080 hours, the 2.00 credit beside 6.10 of cash in lieu still meeting 30.60, then column 6B, column 6C and page 2’s hourly credit table.
How it appears on Form WH-347
- Column 6A is the cash hourly rate paid. On the January 2025 revision this is the wage only; cash paid in lieu of fringe is not folded into it.
- Column 6B is the total fringe benefit credit for the week: the hourly amount paid into plans, multiplied by the worker’s total hours across all classifications.
- Column 6C is the payment in lieu of fringe: the hourly cash paid instead of plans, multiplied by the hours. Cash in lieu is part of the worker’s gross; plan contributions are not.
- Page 2, the fringe certification, is one box for fringe paid in cash, to plans, or both. When 6B has an amount, the hourly credit table under it gives each plan’s name, type and number, funded or unfunded, and each worker’s hourly credit under it; cash in lieu needs no entry there. The Statement of Compliance guide shows the three cases.
Watch it done, 2:55. The rule from this guide on the sample project in EG Certified Payroll: the determination’s 22.50 plus 8.10, a worker paid all in cash, the dollar-short rate shown in red before Check runs, columns 6A, 6B and 6C on page 1, the fringe box on page 2, and Apply fix.
Fringe on overtime hours
Fringe is owed on every hour worked, overtime hours included, at the straight fringe rate. It is never multiplied by one and one-half, and it is not part of the base the overtime premium is figured on. The overtime guide has the arithmetic.
Where a fringe is stated as a percentage. Some determinations state a fringe as a percentage of the basic rate rather than an hourly amount. Compliance is then the stated percentage times the basic rate, converted to an hourly figure for the comparison.
Common questions
Can I pay the whole obligation in cash and skip the plan?
Yes. Paying the fringe amount as cash on top of the basic rate satisfies the determination. It shows in column 6C, and it is part of gross pay, so it is subject to withholding.
My health plan costs more than the fringe. Can the excess cover a short cash rate?
No. The basic hourly rate must be paid in cash. Plan contributions can only be credited against the fringe portion of the determination, never against the basic rate.
Does vacation pay count as fringe?
Vacation and holiday pay are listed benefits, when paid under a bona fide plan. A discretionary bonus is not.
How do I turn a health plan premium into an hourly fringe credit?
Annualize it: divide the plan’s cost for the year by all the hours the worker worked that year, on private and covered work together. 4,160 a year over 2,080 hours is 2.00 an hour against the fringe; the cash rate still has to meet the basic rate on its own.
Check it before you sign it
EG Certified Payroll shows the required basic-plus-fringe beside what you pay on every line, checks the sum before approval, and offers the fix when a rate falls short. The video near the top of this page changes a rate mid-job on the sample project: the new rate from its date, the earlier one kept, and the approved week unchanged. The video under How it appears on Form WH-347 puts this guide’s rule on the sample’s numbers: 22.50 plus 8.10, the dollar-short rate in red, and columns 6A, 6B and 6C. The video under A plan’s yearly cost as an hourly credit enrolls a worker in a health plan at 4,160 a year over 2,080 hours and follows the 2.00 credit to column 6B and page 2.
See EG Certified Payroll (WH-347)Free trial, the full product; every printed page carries a TRIAL COPY mark until a license is activated. Excel for Windows or Mac.
More in this series: Overtime on Certified Payroll: The Rate, the Base and the Hours · How to Fill Out Form WH-347, Column by Column · All certified payroll guides
★★★★★
“Most likely one of the best freelancers I’ve had the opportunity of working with. I would highly recommend David for any complex VBA coding. We’ll be working with him again in the future.”
VBA Development Client · via Upwork, 2020
5.0★ across 230+ client reviews · 100% Job Success on Upwork · Building Excel tools since 2010 · Read the reviews →